
Kalshi suspends Trump mention markets at CFTC’s request
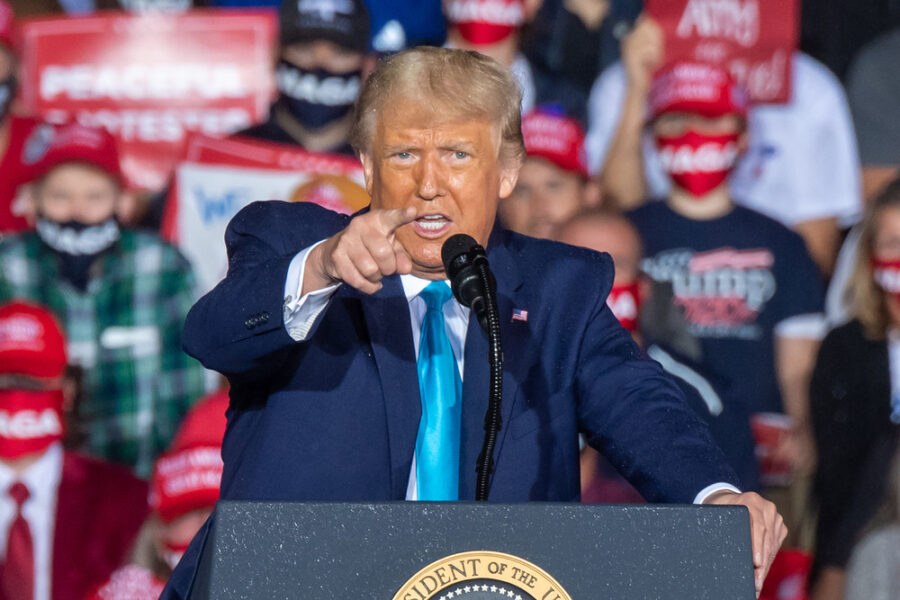
Prediction market platform Kalshi has suspended several US President Trump mention markets at the request of the Commodity Futures Trading Commission (CFTC).
According to CNBC, the company confirmed on Tuesday it had paused trading in several markets, including ones asking traders to predict which nicknames Trump would use before 2027, which words he would say this month, and which countries or companies he would mention before the end of the month.
A CFTC spokesperson said the markets “may be susceptible to manipulation.”
The suspension follows a CFTC order issued on 13 November that opened proceedings into whether Kalshi’s self-certification of the contracts, first filed in February 2025, was false. The regulator said it “presumptively believes the certification is false,” and Kalshi has until 11 December to show that the contracts comply with federal rules.
Mention markets focus on specific words or phrases used in speeches, broadcasts and other public appearances. In September, CFTC staff warned that such contracts may be vulnerable to manipulation and said exchanges must show heightened safeguards, including surveillance of people who can control the outcome.
The markets have previously raised insider trading concerns. Former White House teleprompter operator Gabriel Perez used advance access to the president’s speeches to trade on related Kalshi markets, and the CFTC imposed a three-year trading ban and ordered him to pay more than US$172,000, including a US$65,000 civil penalty.
Following that case, the CFTC began an internal review of mention markets and asked Kalshi to remove its sports-related mention markets.
Mention contracts had been generating around US$90 million in monthly trading volume, according to Reuters. Similar Trump mention markets remain active on rival platform Polymarket.
Kalshi has previously defended mention markets, arguing that statements by prominent figures can trigger significant movements in financial markets.
Kalshi is also facing legal action from several US states, whose regulators argue that its markets should fall under state gambling laws rather than federal oversight by the CFTC.

Dig Deeper
Related stories
 2026/09/23: Kalshi seeks CFTC approval on margin trading; CFTC issues advisory on “mention” markets
 2026/09/30: CFTC examining prediction market promotions and incentive programs
 2026/08/14: White House claims no involvement in Lakers sale to Jared Kushner’s brother
 2026/11/12: Kalshi under CFTC investigation over event contract submissions
2026/09/23: Kalshi seeks CFTC approval on margin trading; CFTC issues advisory on “mention” markets
2026/09/30: CFTC examining prediction market promotions and incentive programs
2026/08/14: White House claims no involvement in Lakers sale to Jared Kushner’s brother
2026/11/12: Kalshi under CFTC investigation over event contract submissions
The Backstory
Regulators move from warnings to intervention
Kalshi’s suspension of several Trump-related “mention” markets marks a shift in the Commodity Futures Trading Commission’s approach to prediction markets: from issuing warnings about vulnerable products to directly challenging contracts already listed or self-certified by an exchange. The CFTC’s request that Kalshi pause markets tied to words, nicknames, companies and countries President Donald Trump might mention before specified dates follows months of scrutiny over whether these products can be fairly surveilled when the outcome depends on the conduct of one person or a small group with advance knowledge.
The immediate regulatory concern is manipulation. Mention markets settle on whether a person says a particular word or phrase, attends an event or interacts with someone. That creates a different risk profile from broader economic or political contracts, where outcomes typically depend on outside data, public votes or measurable events. In September, the CFTC said these markets may present a “heightened risk” because settlement can turn on conduct that is not independently generated or externally verifiable. Kalshi had already excluded such contracts from a separate proposal to offer leveraged trading, underscoring how even the company’s expansion plans treated mention markets as a more sensitive category.
The current suspension also puts pressure on Kalshi’s self-certification model. Federally regulated prediction exchanges can list event contracts without advance CFTC approval if they certify that the products comply with the Commodity Exchange Act. The CFTC’s Nov. 13 order opening proceedings into whether Kalshi’s certification was false signals that the agency is prepared to test the limits of that process when it believes a contract may be susceptible to manipulation.
The insider-trading case that changed the debate
The CFTC’s hardening stance did not emerge in isolation. Mention markets drew wider attention after a former White House teleprompter operator, Gabriel Perez, used advance access to presidential speeches to trade on Kalshi markets linked to what Trump would say. The CFTC barred Perez from trading for three years and ordered him to pay more than $172,000, including a $65,000 civil penalty. The case gave regulators a concrete example of how information asymmetries can undermine confidence in event contracts tied to scripted or prepared remarks.
That enforcement action narrowed the policy debate. Prediction market operators have argued that public statements by presidents, central bankers and business leaders can move financial markets, making related contracts useful for hedging and forecasting. But the Perez case showed that the outcome of some contracts could be influenced or known by staffers, advisers, production crews or others close to the speaker before the public had any chance to trade on equal terms.
After that case, the CFTC began an internal review of mention markets and asked Kalshi to remove sports-related versions. The agency’s concern now extends beyond one trader or one speech. It is asking whether the structure of the product category creates incentives for insiders to trade or for people with influence over the outcome to alter behavior. That question is central to the proceedings Kalshi now faces.
Kalshi’s growth strategy meets tighter scrutiny
Kalshi has been trying to broaden prediction markets from niche political and economic wagers into a more mainstream financial product. One step was its request for CFTC approval to offer margin trading on some event contracts, a plan described in Kalshi’s filing for margin trading approval. Margin would allow eligible traders to use borrowed funds on certain contracts, potentially making long-dated markets more attractive to institutional participants accustomed to leverage in equities and derivatives.
But that proposal also highlighted regulatory fault lines. Kalshi said leverage would not be available for sports, culture or mention markets, and that capital requirements would rise as contracts approached settlement. The carveout reflected a recognition that not all event contracts carry the same risks. It also came the same day the CFTC issued its advisory warning that mention markets require contract-specific analysis and safeguards.
The exchange is facing scrutiny on more than one front. The CFTC is separately examining Kalshi’s event contract submissions, including whether procedural requirements were met for a small number of products. Kalshi has said many of the contracts at issue were not live and that the matter involved a procedural error, but the investigation adds to a broader pattern: regulators are looking more closely at how exchanges certify, launch and monitor new markets as trading volumes grow.
Sports leagues push the integrity argument
Sports contracts have intensified the jurisdictional and integrity disputes around prediction markets. The NFL has urged the CFTC to impose tougher rules, arguing that sports-related contracts raise risks for participants and for the integrity of games. In recommendations submitted to the CFTC, the league called for a minimum age of 21, restrictions on contracts that could be manipulated by one player and a ban on mention contracts tied to broadcasts.
The league’s concerns overlap with the CFTC’s emerging focus. A contract on whether a kicker misses a field goal, whether a quarterback’s first pass is incomplete or whether a broadcaster says a certain phrase could turn on decisions by a small number of people. That makes market surveillance more complex than for contracts tied to final scores, standings or other aggregated outcomes. The NFL also wants platforms to coordinate with sports governing bodies on banned-participant lists, including employees who may have access to nonpublic information.
The sports debate matters for Kalshi because state regulators increasingly argue that sports event contracts resemble gambling and should fall under state betting laws. Kalshi and other operators counter that their products are federally regulated derivatives. The CFTC has generally supported federal jurisdiction in disputes with states, but its skepticism toward certain contract designs shows that federal oversight does not mean every market will be permitted.
Promotions, consumer safeguards and political stakes
The CFTC’s concerns are not limited to contract design. It is also examining promotional and incentive programs used by prediction market operators, including offers described as risk-free or guaranteeing profits. That review reflects another regulatory priority: ensuring that rapid customer acquisition does not come at the expense of market integrity or consumer protection.
Problem-gambling advocates have pressed for safeguards such as age verification, self-exclusion, risk disclosures and responsible-engagement tools. Their arguments have gained traction as prediction markets move closer to the consumer betting ecosystem, particularly through sports and culture contracts. Operators seeking to be treated as financial exchanges face pressure to show that their compliance systems are closer to derivatives markets than online sportsbooks.
The Trump mention markets add a political dimension. Contracts tied to presidential speech sit at the intersection of markets, government access and public trust. The broader atmosphere has already been sensitive, with controversy over financial dealings linked to Trump and his circle, including scrutiny described in coverage of the Lakers sale to Josh Kushner and criticism of proposed tools that could provide faster access to Trump’s social media posts. Even if such matters are separate from Kalshi’s contracts, they sharpen concerns that political proximity can translate into tradable advantage.
What the CFTC’s decision could set in motion
Kalshi has until Dec. 11 to show that the suspended contracts comply with federal rules. The outcome could help define how far self-certification extends and what types of event contracts are too vulnerable to manipulation to list without enhanced safeguards. A narrow decision focused on Trump mention markets would still reverberate across products tied to speeches, interviews, broadcasts and public appearances. A broader ruling could force exchanges to rethink entire categories of contracts.
The stakes are commercial as well as regulatory. Mention contracts have generated significant trading volume, and rivals such as Polymarket continue to offer similar Trump markets. If the CFTC restricts Kalshi while comparable offshore or differently structured platforms keep operating, the agency may face questions about competitive impact and enforcement reach. If it permits the markets with conditions, exchanges will likely need stronger surveillance around insiders and people who can influence outcomes.
For the prediction market industry, the case is a test of its central claim: that event contracts can function as regulated financial instruments rather than unlicensed gambling or speculative entertainment. The CFTC’s latest move suggests that growth alone will not settle that question. Contract design, information access and manipulation controls will.