
Genius Sports ups FY26 revenue expectations to over US$1 billion, after strong 3Q26 results
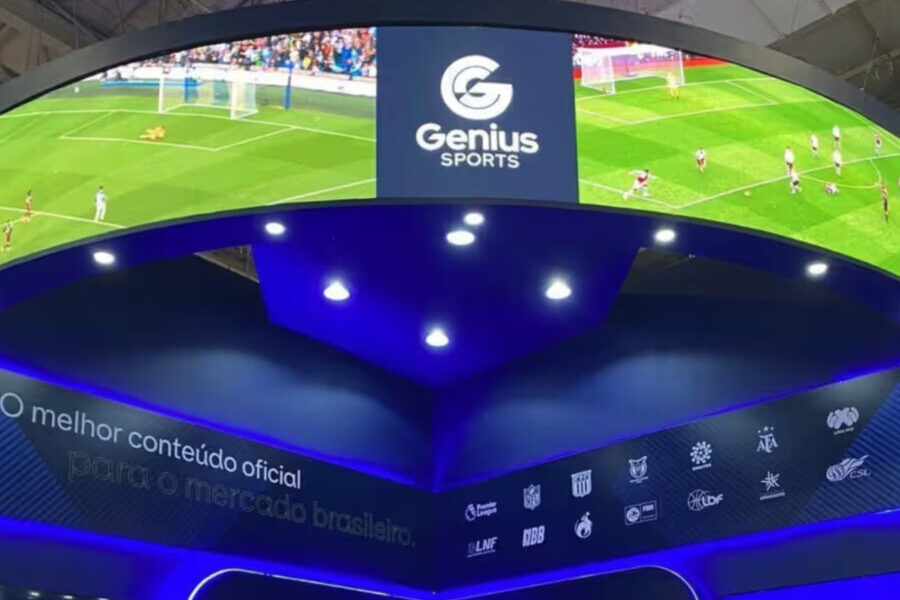
Genius Sports has raised its full-year group revenue guidance for 2026 to US$1.01 billion -US$1.03 billion, increasing its expected adjusted EBITDA guidance to US$287million – US$297 million amongst strong 3Q26 results.
According to its results release on Thursday, group revenue for the third quarter amounted to US$270 million, up by 62% yearly.
The group also registered its first quarter of positive operating income, reaching US$10 million, however the group did register a group net loss of US$15.7 million – a US$16 million improvement year-on-year.
Genius Sports also recorded Group Free Cash Flow of US$54 million, representing 61% conversion, and Unlevered Free Cash Flow of US$69 million, representing 80% conversion.
Speaking of the results, Genius Sports Founder and CEO Mark Locke noted that “Our predictable Betting business, expanding Media capabilities and growing opportunities in prediction markets position us to capture greater value from the data, technology and infrastructure we have spent 25 years building.”
The CEO also doubled down on its recent acquisition of scaled media platform Legend, in a transaction that was valued at up to US$1.2 billion, noting that “Legend is also creating additional commercial value, and we are seeing the benefits of our combined scale. Our strategy is working, and we are well positioned to deliver sustained growth, profitability and free cash flow.”
During the third quarter, the group’s Betting Technology, Content & Services arm saw a 33% increase in revenue to US$153 million, while its Media Technology, Content & Services arm saw a 126% yearly increase in revenue to US$116.9 million, primarily driven by the Legend acquisition.
The group’s strong third quarter results come amongst significant updates for the company, including partnering with the two largest prediction market platforms Polymarket and Kalshi “to provide a broad portfolio of content, integrity services and marketing solutions.”
The group also launched a prediction market platform comparison site, Prediction.com.

Dig Deeper
Related stories
 2026/02/05: Genius Sports enters definitive agreement to acquire digital sports and gaming media network Legend
 2025/12/04: Aristocrat Interactive launches online Cash Express Legend Buffalo game
 2025/07/03: Genius Sports running a ‘two-horse race,’ Truist analyst says
2025/02/07: Genius Sports aspires to a ‘new standard for in-play betting’ with latest BetVision release
2026/02/05: Genius Sports enters definitive agreement to acquire digital sports and gaming media network Legend
2025/12/04: Aristocrat Interactive launches online Cash Express Legend Buffalo game
2025/07/03: Genius Sports running a ‘two-horse race,’ Truist analyst says
2025/02/07: Genius Sports aspires to a ‘new standard for in-play betting’ with latest BetVision release
The Backstory
From data supplier to broader sports media platform
Genius Sports’ latest guidance increase reflects a business that has been trying to move beyond its original identity as a sports data supplier and into a broader role across betting, media, advertising and fan engagement. The company’s third-quarter performance, including faster revenue growth and its first quarter of positive operating income, is the clearest financial marker yet of that shift.
The strategy has been developing for years. Genius built its position on official sports data, integrity monitoring and technology services for sportsbooks, leagues and media companies. That foundation gave it access to live events, data rights and operator relationships that are difficult for new entrants to replicate. The company has increasingly used those assets to build products around in-play betting, targeted advertising and interactive broadcasts, where margins can be higher than traditional data distribution.
That context helps explain why the company’s raised 2026 outlook is not just about one strong quarter. It follows a sequence of moves designed to deepen its role in the betting supply chain and capture more value from sports fans before, during and after games. The company’s commentary around predictable betting revenue, expanding media capabilities and prediction-market opportunities points to a model that depends on scale, rights and technology working together.
Legend deal reset the scale of the media business
The biggest step in that expansion was Genius Sports’ agreement to buy Legend, a digital sports and gaming media network, in a transaction valued at up to $1.2 billion. The deal included $900 million payable at closing and a potential $300 million earnout tied to profitability and cash flow. Genius said the acquisition would be immediately accretive to adjusted EBITDA margins and free cash flow conversion, while supporting at least 20% annual revenue growth through 2028.
The acquisition gave Genius a larger direct audience and more advertising inventory. Legend’s network monetizes sports fans across owned and operated digital properties and syndicates sports and betting content through major publications. At the time of the announcement, Legend was credited with 320 million annual visits and 118 million unique visitors in 2025, with more than two-thirds returning regularly. That audience was strategically important because Genius already had the betting data, trading tools and operator relationships needed to turn attention into commercial activity.
The company positioned the deal as a way to connect sports fans, advertisers and betting operators through FANHub, its fan activation platform. In practical terms, it added a performance marketing layer to Genius’ data and technology business. The immediate effect is visible in the current results: the Media Technology, Content & Services unit more than doubled year over year, largely because of Legend. That growth also explains why investors are focused not only on betting revenue but on how efficiently Genius can integrate a larger, more complex media operation.
The market reaction when the deal was announced showed the trade-off. As reported in Genius Sports’ agreement to acquire Legend, analysts pointed to investor concerns over performance marketing businesses and added complexity. Genius argued the acquisition would accelerate margin expansion, free cash flow generation and sports fan monetization. The third-quarter update suggests management is using the deal to support a higher revenue base sooner than previously expected.
Analysts saw a two-player market with high barriers
Before the latest earnings upgrade, some analysts had already framed Genius as one of the few companies positioned to benefit from the professionalization of sports betting technology. In July, Truist Securities initiated coverage with a buy rating, describing Genius as a provider of data and technology solutions across sports betting, media and sports. The report said the company had roughly 700 partnerships across leagues, teams, sportsbooks and broadcasters in more than 150 countries.
That coverage emphasized a market structure favorable to incumbents. Truist described the sports betting data business as a “two-horse” race between Genius and Sportradar, with high barriers to entry and lower risk of major contract losses. Exclusive and long-term data relationships, including with major leagues such as the NFL and NCAA, were presented as central to the company’s visibility. Those rights are important because regulated sportsbooks rely on fast, official data to price in-play markets and manage risk.
The same analysis highlighted Genius’ push into higher-margin areas such as advertising and proposition betting. Its media business was described as a distinct growth opportunity because the company could use real-time sports data to target fans more efficiently for sportsbooks and other brands. That theme now appears more central after the Legend transaction and the current jump in media revenue.
The risks identified then remain relevant. As noted in Truist’s analysis of Genius Sports as a two-player race, contract losses, expensive renewals, higher betting taxes and the growth of prediction markets could pressure the stock or margins. The current quarter suggests Genius is trying to turn some of those risks into opportunities, particularly by partnering with prediction-market operators rather than treating them solely as competitors.
BetVision illustrated the in-play betting thesis
Genius’ product strategy has been most visible through BetVision, its streaming and in-play betting product. The platform combines live sports streams with real-time statistics, interactive features and betting functionality. Its purpose is to reduce friction for bettors, especially in micro markets where odds move quickly and delays can cause users to abandon wagers.
The company has argued that the U.S. market remains underdeveloped for in-play betting compared with Europe. BetVision is designed to change that by embedding odds, statistics and bet placement into the viewing experience. In an interview around the latest BetVision release, Genius executives said the product’s integrated bet slip materially increased the likelihood that users would complete a bet rather than leave the stream to place a wager elsewhere.
That matters for Genius because in-play betting depends heavily on the assets it already controls or supplies: low-latency video, official data, modeling, pricing tools and integrity systems. The more betting shifts from pregame wagers to live player props and micro markets, the more valuable those capabilities become. The company’s current growth in betting technology and media is tied to the same trend: sports consumption and wagering are becoming more immediate, personalized and data-driven.
As detailed in Genius Sports’ latest BetVision release, the company has also linked product expansion to integrity safeguards. That is a central issue as player props, college sports and micro-betting draw scrutiny from regulators and leagues. Genius’ argument is that legal, monitored markets supported by official data are safer than pushing demand to offshore or black-market platforms.
Brazil and prediction markets widened the opportunity set
Genius has also been broadening its geographic and product reach. In Brazil, the company partnered with Rei do Pitaco, a fantasy sports and betting operator with more than nine million registered users. The deal gave Rei do Pitaco access to BetVision, official data and in-play trading support across competitions including the Premier League, Brasileirao Serie A, Italian Serie A, NFL, AFA and Liga MX.
The Brazil agreement showed how Genius packages multiple capabilities into one commercial relationship: official data, live streaming, trading support and digital advertising. In a newly regulated and fast-growing betting market, that bundle can help operators differentiate their sportsbooks and manage in-play betting more effectively. As covered in Genius Sports’ partnership with Rei do Pitaco in Brazil, the deal also extended into advertising around major sports events, reinforcing the company’s effort to connect betting technology with fan acquisition and monetization.
The latest quarter adds another emerging area: prediction markets. Genius said it has partnered with Polymarket and Kalshi to provide content, integrity services and marketing solutions, while also launching Prediction.com, a comparison site for prediction market platforms. That move is notable because prediction markets have been viewed by some analysts as a potential threat to traditional sportsbooks. By supplying them with data, integrity tools and media services, Genius is positioning itself to earn revenue regardless of whether consumer activity flows to sportsbooks, prediction markets or both.
Why the guidance increase carries strategic weight
The raised 2026 outlook indicates management believes the company’s expansion is translating into operating leverage. Revenue growth alone would be less meaningful if it came with widening losses or heavy cash burn. Instead, Genius reported positive operating income for the quarter, improved net loss, strong free cash flow conversion and higher adjusted EBITDA expectations.
The stakes are high because Genius is now asking investors to underwrite a more diversified company. Its core betting data business offers visibility, but the higher-growth parts of the story sit in media, advertising, in-play products and emerging market categories. Those areas can deliver stronger margins and cash flow, but they also require integration discipline, continued rights access and regulatory adaptability.
The current results suggest the company is making progress on that balance. Legend has accelerated media revenue, BetVision supports the in-play betting thesis, Brazil shows international operator demand and prediction-market partnerships expand the addressable market. The question now is whether Genius can sustain that momentum while reducing complexity and proving that its broader platform can produce durable profits, not just faster top-line growth.