
CEO upbeat in Flutter third-quarter earnings call
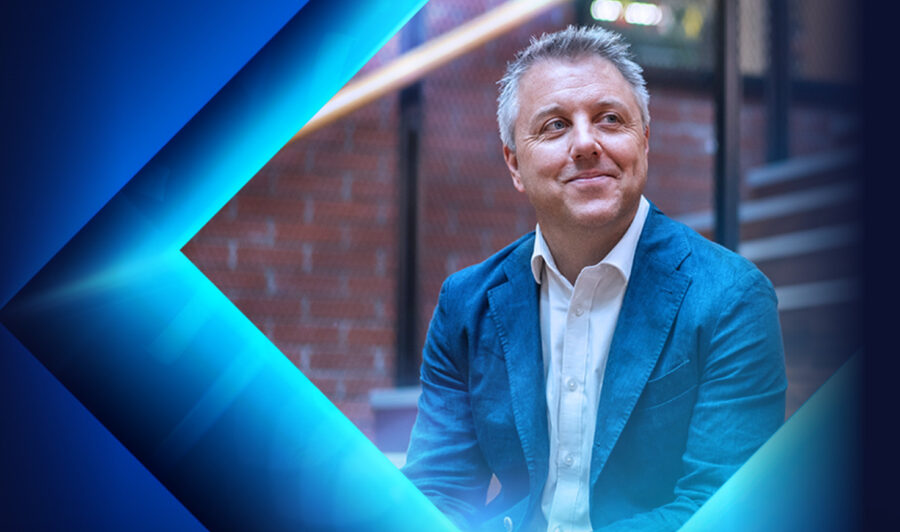
In his first earnings call as Flutter Entertainment CEO, Dan Taylor strove to strike a positive tone, saying that, in his first five weeks on the job, he’d been impressed with Flutter’s United States team and its “portfolio of fantastic brands.”
“But we will be more demanding,” Taylor cautioned, including making further cost cuts. He said his priorities would include operating at the pace of the rest of the industry and investing with discipline in the US “I am encouraged by the momentum we are building,” he said, but hard choices and strong execution were needed.
In the US, Taylor said, FanDuel had made market-share gains during August and September. Although sports results were unfavorable, he added, FanDuel was performing ahead of expectations.
Taylor deemed traditional online sports betting products to be superior to their prediction-market equivalents, although their marketing costs were higher. That being said, he called event contracts “a very meaningful long-term opportunity … and we’re just getting going.” FanDuel Predicts, he said, “is now genuinely competitive,” doing 80% to 85% of its trades in OSB.
“We are investing at a level that we believe will position us well,” Taylor said of prediction markets. He remarked that FanDuel Predicts was scooping up typical sportsbook customers.
Internationally, the CEO called Flutter a “regional powerhouse,” citing its market share in Italy, the United Kingdom and Southeast Asia. This included double-digit market-share growth in the UK and Ireland during the World Cup.
Taylor said he was “clearly very disappointed” by the Brazilian ban on iGaming and OSB. However, he said Flutter was ready to resume operations should the edict be lifted.
Chief Financial Officer Rob Coldrake added that Flutter’s stock-repurchase program was suspended “for the foreseeable future.” This was attributed to Flutter’s high leverage of 4.6 times cash flow, which Coldrake aimed to get down to two times or 2.5 times. The fourth quarter, he added, was living up to expectations.
Of prediction markets, Coldrake said, “we are increasingly well positioned to capture this opportunity. I’m encouraged by the underlying trajectory of the business.”
Professing candor, Taylor said the early FanDuel prediction-market products were “not impressive.” But the results now look like OSB, he continued, with a lower player-acquisition cost.
With regard to the market-making business, Coldrake said he saw an advantage but was more focused on delivering 2026 revenue guidance. “We see that [business] building next year. We’re really pleased with the progress we’re making.”
In iGaming, Taylor said the third quarter saw 13% market growth. “That doesn’t really surprise us,” he said of the apparent slowdown. “We feel good about our competitive position.”
The CEO was particularly impressed, he said, with Alberta, where iGaming and OSB were ramping up at double the rate of Ontario. This, he remarked, renewed his confidence in US expansion of iGaming, still unavailable to the vast majority of the country.
Taylor continued he was not happy with the midterm election results in Nebraska, where OSB went down to defeat. “But we feel good about the (overall) prospect for the next few years,” he elaborated, explaining that he was not optimistic for “a strong pipeline of further state openings.”
Seemingly chastised for an increase in marketing spending, Coldrake responded that it was an increase in promotional generosity, not in advertising, underpinned by increases in market share. Player promotions were he said, now in line with the rest of the market. “We feel vindicated in the level of investment we made in Q2,” Taylor added.
One Wall Street analyst posited that FanDuel was driving a vicious cycle of promotions. Taylor responded that the increased outlays were bringing FanDuel up to the level of its competitors and would continue.
Coldrake also was unfazed by early season injuries in the NBA. These were, he said, nothing new. “It’s pretty early days,” the CFO commented. Also, “there was some (wagering) momentum held over from the end of last year,” in line with FanDuel’s expectations.
World Cup action had brought 2.3 million players to Flutter. Taylor said one-third of those customers had been dormant and 600,000 were new, and “that’s helped us carry through to September. That’s put us in good stead as we started the NFL season.”
Having been hit with higher gaming taxes in the UK, Flutter had to “make some pretty challenging decisions,” Taylor said. These included pink-slipping 1,400 employees. But Flutter was now set up well, he added, and wasn’t curbing its player generosity in the British Isles.
“They will all be painful,” he said of the alternatives facing Flutter, “and the choices in the UK were very painful.” But, he added, “we think it will underpin further share gains going forward.”
David McKee is an award-winning journalist who has three decades of experience covering the gaming industry.

Dig Deeper
Related stories
The Backstory
Leadership change followed a year of harder questions
Dan Taylor’s first earnings call as Flutter Entertainment chief executive landed after several quarters in which investors pressed the FanDuel parent on whether its U.S. strategy was becoming more expensive, more complex and less predictable. The company’s core message has been consistent: FanDuel remains one of the strongest assets in U.S. online sports betting and iGaming, but keeping that position requires heavier product investment, more promotions and tighter cost control elsewhere.
That balance has become harder to explain as sports results, taxes, prediction markets and state-launch costs all moved against near-term earnings. In March, executives were already being pushed for details they did not provide, with Chief Financial Officer Rob Coldrake telling analysts Flutter did not “obsess about handle” because it could be inflated by promotions and parlays. That call, covered in Flutter executives’ tense exchange with analysts, showed the early contours of the debate now facing Taylor: whether FanDuel can defend share without undermining margins.
Peter Jackson, Taylor’s predecessor, framed 2025 as a year of investment rather than retrenchment. He argued that the company had ended the prior year with a larger business than expected and that product changes, including parlay expansion and iGaming improvements, would support longer-term growth. But the questions did not fade. By the time Taylor took over, Flutter had already lowered guidance, reshuffled FanDuel leadership, expanded cost-saving plans and moved prediction markets from a watching brief to an active strategic priority.
FanDuel’s U.S. engine hit turbulence
The U.S. business has been Flutter’s most important growth driver, but its performance has become more exposed to the calendar and to customer behavior around marquee sports. In one earlier call, Jackson and Coldrake pinned weaker results on the NFL, saying less compelling playoff content and the absence of star players reduced the type of betting activity that typically benefits FanDuel. The company said bettors pulled back when matchups lacked broad appeal, curbing handle and parlay activity.
That explanation, detailed in Flutter’s account of NFL-driven quarterly weakness, mattered because FanDuel’s U.S. model relies heavily on sophisticated same-game parlays, broad customer engagement and the ability to hold share through major sports seasons. Executives said non-NFL trends remained positive and pointed to Missouri as one of FanDuel’s most successful state launches. But the episode underscored that even market leaders can see earnings swing when sports outcomes, team popularity or customer appetite move against them.
Flutter later tried to reset the narrative around U.S. momentum. In its second-quarter update, Jackson highlighted higher FanDuel revenue, growth in players and stronger gross-revenue margins. He also emphasized FanDuel Rewards, new casino titles and expanded parlay options. That call, summarized in Flutter’s celebration of second-quarter results, suggested management believed product depth could offset volatility in sports results. Taylor inherited that thesis, but also the burden of proving it under a less forgiving earnings backdrop.
Guidance cuts made investment the central issue
The pivotal moment came in August, when Flutter reduced full-year revenue projections by US$395 million and cash-flow expectations by US$210 million. The company attributed part of the reduction to efforts to strengthen FanDuel’s sportsbook proposition and accelerate momentum. Jackson, speaking in his final earnings call as CEO, cast the decision as a deliberate reinvestment in the United States, even though it weighed on near-term earnings.
The move, examined in Flutter’s guidance cut and increased FanDuel investment, sharpened analyst focus on whether promotions were becoming structurally higher. Coldrake described the spending as disciplined and said paybacks were excellent. Jackson pointed to World Cup and NBA engagement, record Major League Baseball handle and the rollout of loyalty features as evidence that the spend was working.
Still, the guidance cut had consequences. It made cost savings more central to Flutter’s story and elevated leverage reduction as a financial priority. Coldrake said the company was targeting debt of two times to 2.5 times cash flow over the long term, while also expanding plans to reduce costs through synergies and artificial intelligence. Taylor’s later comments about being “more demanding” and making further cuts fit into that sequence. The company is not just chasing growth; it is trying to pay for growth while reassuring investors that profitability has not been deferred indefinitely.
Prediction markets moved from risk to opportunity
Flutter’s tone on prediction markets also evolved. Early in the year, executives treated them mainly as a regulatory and competitive uncertainty. They said cannibalization appeared limited and described event contracts as a potentially incremental way to acquire customers in states without legal online sports betting. Analysts repeatedly asked how much Flutter would spend, how the products might affect FanDuel and whether the company had an edge.
By May, when Flutter executives stuck largely to generalities during another earnings call, Jackson acknowledged the “noise” around prediction markets and said legal uncertainty would persist until higher courts clarified the rules. He also described market-making as a way to monetize FanDuel’s pricing capabilities. The company shuttered FanDuel Picks and FanDuel TV’s racing network during that period, showing it was willing to close noncore projects while testing new ones.
The stance became more assertive by the time Jackson handed off to Taylor. Flutter said prediction markets were cannibalizing traditional betting only in the low single digits and emphasized their usefulness in states where FanDuel could not yet offer online sports betting. The strategic logic is straightforward: If event contracts can introduce consumers to FanDuel before legalization, the company may lower future acquisition costs and build brand familiarity ahead of competitors. Taylor’s view that FanDuel Predicts is now competitive and resembles online sports betting in usage is the next step in that argument.
Taxes and regulation narrowed the margin for error
Rising gaming taxes have complicated the growth story on both sides of the Atlantic. In the U.S., Illinois’ handle tax prompted FanDuel to prepare a surcharge, with Jackson calling the levy harmful to customers and sports integrity. New Jersey and Illinois also weighed on gross margins, while executives warned that other states might make noise about higher taxes even if they did not expect to exit markets.
The tax issue matters because online betting operators have long argued that scale will drive profitability. Higher levies can absorb part of that scale benefit and force operators to choose among lower promotions, customer surcharges, reduced marketing or lower margins. Flutter’s answer has been to lean on scale, product and cost efficiency. That is also why management has repeatedly said FanDuel’s depth, pricing and parlay products give it an advantage over less complete prediction-market offerings.
Outside the U.S., regulation has been just as important. Flutter has emphasized Italy, the United Kingdom, Ireland, Brazil and other markets as sources of diversification, while acknowledging that policy shifts can quickly alter the outlook. Brazil was initially presented as a major long-term opportunity, albeit one requiring significant investment in a market with existing competitors. Taylor’s disappointment over Brazil’s ban on iGaming and online sports betting reflects how quickly that opportunity can be interrupted by regulatory change.
What Taylor is trying to prove
Taylor’s first call was therefore less a clean beginning than the latest stage in a reset. Flutter has a market-leading U.S. sportsbook, a growing iGaming business, international scale and a new prediction-market platform. It also has elevated leverage, suspended buybacks, tax pressure, regulatory uncertainty and investor scrutiny over promotional spending.
The through line from Jackson’s final months to Taylor’s debut is disciplined aggression. Flutter is spending where it believes the returns justify it, especially FanDuel, prediction markets and iGaming. At the same time, it is cutting costs, reducing leverage and pruning weaker assets. Taylor’s challenge is to show those moves can coexist: that FanDuel can gain share without triggering destructive promotional warfare, that prediction markets can add customers rather than dilute economics and that international setbacks will not derail the broader portfolio.
That is why the upbeat tone of the latest call carries stakes beyond one quarter. Investors have already heard that sports results were unfavorable, taxes are rising and new opportunities require capital. Taylor now has to convert the inherited strategy into measurable proof that Flutter’s scale can still compound earnings, not just revenue.