
Alberta igaming handle nears CA$1.3 billion in third month since launch
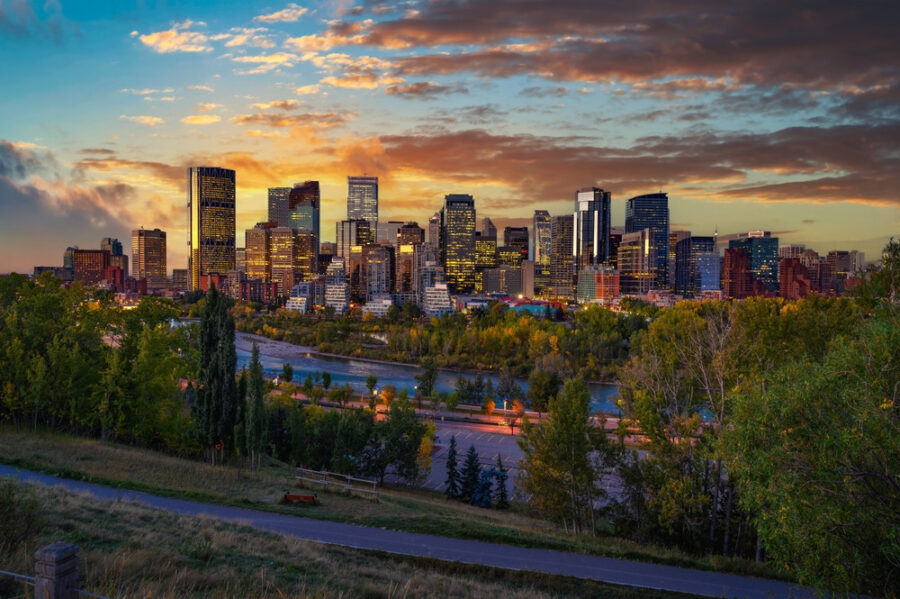
Canada’s Alberta igaming market generated CA$1.28 billion (US$913 million)1 CAD = 0.7135 USD
2026-10-27Powered by CMG CurrenShift in wagers in September, up 20% from CA$1.06 billion (US$756 million)1 CAD = 0.7135 USD
2026-10-27Powered by CMG CurrenShift in August and 135.3% higher than July’s CA$542.9 million (US$387 million)1 CAD = 0.7135 USD
2026-10-27Powered by CMG CurrenShift. The figures, published by the Crown corporation that conducts and manages Alberta’s regulated market, the Alberta iGaming Corporation (AiGC), show that non-adjusted gross gaming revenue (NAGGR) also rose in September, reaching CA$56.6 million (US$40.4 million)1 CAD = 0.7135 USD
2026-10-27Powered by CMG CurrenShift, the highest total over the three months since its launch.
This was a 30.7% month-on-month increase from CA$43.3 million (US$30.9 million)1 CAD = 0.7135 USD
2026-10-27Powered by CMG CurrenShift and a 155% increase compared to July, which generated CA$22.2 million (US$15.8 million)1 CAD = 0.7135 USD
2026-10-27Powered by CMG CurrenShift in NAGGR.
Online casinos accounted for the majority of NAGGR, generating CA$42.8 million (US$30.5 million)1 CAD = 0.7135 USD
2026-10-27Powered by CMG CurrenShift and holding a 75.6% market share. This was followed by sports betting with reported CA$11.1 million (US$7.9 million)1 CAD = 0.7135 USD
2026-10-27Powered by CMG CurrenShift in NAGGR, accounting for 19.5% of the market, and live casino games, which posted CA$2.8 million (US$2.0 million)1 CAD = 0.7135 USD
2026-10-27Powered by CMG CurrenShift in NAGGR and a 4.9% market share.
“Early results indicate that Albertans value the strong oversight and greater accountability offered by a regulated market,” AiGC CEO Dan Keene said in a statement. “We hope to continue educating Albertans about the risks associated with illegal offshore sites and move them onto regulated platforms where they have rights and recourse when igaming,” he added.
Alberta’s regulated market officially launched on 13 July with 15 operators; since then, it has expanded to 24. DraftKings, Stake, and theScore Bet are just a few of the operators available in the province.
Alberta’s regulated market is proving popular among Albertans. In the first week of launching, Vancouver-based geolocation company GeoComply reported over 3.2 million geolocation checks and more than 100,000 Albertans signing up with registered operators. Since then, the number of active player accounts has reached 388,585 as of September.
Charlotte Capewell brings her passion for storytelling and expertise in writing, researching, and the gambling industry to every article she writes. Her specialties include the US gambling industry, regulator legislation, igaming, and more.

Dig Deeper
Related stories
 2025/02/12: NorthStar points to growth in preliminary Q4 results
 2025/01/23: iGaming Ontario switches to monthly reporting as revenue grows
 2026/09/24: iGaming Ontario reports CA$9.7 billion August betting handle, up 19.7% year-on-year
2026/08/27: iGaming Ontario posts record-breaking July with handle reaching CA$9.9 billion
2025/02/12: NorthStar points to growth in preliminary Q4 results
2025/01/23: iGaming Ontario switches to monthly reporting as revenue grows
2026/09/24: iGaming Ontario reports CA$9.7 billion August betting handle, up 19.7% year-on-year
2026/08/27: iGaming Ontario posts record-breaking July with handle reaching CA$9.9 billion
The Backstory
Alberta’s fast start follows a deliberate policy shift
Alberta’s regulated online gambling market entered September with momentum that had been building since before its July 13 launch. The province designed the framework to move players away from offshore sites and into a system where operators are licensed, activity is monitored and consumers have formal recourse. The early numbers now suggest that policy bet is gaining traction, with handle nearly tripling from July to September and gross gaming revenue rising at a similar pace.
The current figures matter because Alberta is only Canada’s second open regulated igaming market, following Ontario. Its launch gave operators another major provincial market and gave policymakers a live test of whether Ontario’s model could be adapted outside the country’s largest province. Alberta did not simply replicate Ontario’s structure. It created the Alberta iGaming Corporation to conduct and manage the market, while Alberta Gaming, Liquor & Cannabis retained a central regulatory role. That split was intended to give the market commercial flexibility while keeping oversight within a provincial framework.
The province also entered the market with clear revenue expectations. Before launch, Service and Red Tape Reduction Minister Dale Nally said Alberta’s market was expected to generate CA$76 million in first-year tax revenue, while positioning player protection as a core justification for regulation. As detailed in the province’s prelaunch plan for a market projected to deliver CA$76 million in first-year tax revenue, Alberta set a revenue-sharing structure under which operators receive 80% of net igaming revenue and the government retains 20%. From operator revenue, 2% is earmarked for First Nations and 1% for social responsibility funding.
Leadership and launch mechanics shaped the rollout
The province’s ability to stand up the market quickly was tied to its choice of leadership. Dan Keene, a longtime Alberta Gaming, Liquor & Cannabis executive, was appointed permanent chief executive of the Alberta iGaming Corporation shortly before launch. His background included oversight of gaming retail services, compliance, online gambling, product development and PlayAlberta.ca, the province’s existing government-run online gambling platform.
That appointment signaled continuity rather than a wholesale break from Alberta’s prior gambling infrastructure. In its report on Dan Keene’s appointment as Alberta iGaming Corporation CEO, Complete iGaming noted that Keene had been involved in standing up the new corporation and had helped develop consumer-facing gaming programs, including the Winner’s Edge loyalty program. Those credentials were relevant because Alberta’s market launch required both operator onboarding and a consumer transition from unregulated or gray-market options to provincially approved platforms.
The launch also arrived with significant industry participation. Alberta initially went live with 15 operators and later expanded to 24. The broader prelaunch pipeline included major U.S. sportsbook and casino brands, international operators and Canadian platforms. That depth was important because a regulated market depends on giving players enough legal alternatives to compete with offshore sites. A market with too few operators risks leaving established player behavior unchanged. Alberta’s early geolocation and account-registration figures indicated that the legal market was not merely available but being actively tested by residents.
Ontario provided the proof of concept
Alberta’s model cannot be understood without Ontario. When Ontario launched its regulated online gambling market in April 2022, it became the first Canadian province to create an open competitive framework for private operators. By the time Alberta launched, Ontario had already demonstrated that a regulated igaming market could produce large wagering volumes, recurring tax revenue and a meaningful shift from offshore play into monitored channels.
Ontario’s scale has continued to set the benchmark. In June, the province recorded CA$9.5 billion in wagers and CA$400.6 million in non-adjusted gross gaming revenue, according to iGaming Ontario data covered in Ontario’s June igaming market report. The market also had 48 operators after Hard Rock Bet launched in the province, underscoring the competitive depth Alberta policymakers and operators were watching.
The following month, Ontario’s growth accelerated again. July handle reached CA$9.9 billion, the highest monthly total since legalization, while gross gaming revenue climbed to CA$414 million. That performance, described in the report on Ontario’s record-breaking July handle, showed that a regulated market could keep expanding even after its initial launch phase. For Alberta, the lesson was not that it could match Ontario’s scale immediately. It was that legal market participation can deepen over time as operators invest, consumers adjust and regulatory norms become familiar.
Casino play is driving both provincial markets
The composition of Alberta’s early market resembles Ontario in one key respect: online casino activity is doing most of the heavy lifting. In Alberta, casino games accounted for more than three-quarters of September non-adjusted gross gaming revenue, while sports betting held a much smaller share. That split reflects a broader pattern across Canadian regulated igaming, where casino products tend to generate steadier volume and higher revenue than sports wagering.
Ontario’s recent data reinforces that dynamic. In August, online casinos represented 90.1% of total cash wagers and 84.5% of non-adjusted gross gaming revenue in the province. As reported in iGaming Ontario’s August betting handle update, casinos generated CA$8.8 billion in wagers and CA$336 million in gross gaming revenue, while sports betting produced CA$843 million in wagers and CA$54 million in revenue. Sports betting remained highly visible, but casino play remained the economic center of the market.
That matters for Alberta’s fiscal projections. A market led by casino revenue can support more predictable monthly revenue than one dominated by sports betting, where margins fluctuate with event calendars and outcomes. It also raises different regulatory considerations. Casino products involve rapid play, high session frequency and large game libraries, all of which increase the importance of product standards, intervention tools and responsible gambling funding. Alberta’s decision to dedicate a portion of operator revenue to social responsibility reflects that risk profile.
Oversight is becoming part of the growth story
Growth alone does not settle the policy debate. Ontario’s experience shows that as regulated igaming expands, enforcement and compliance become more prominent. The province has already taken action against suppliers and operators over product features and advertising issues, including a CA$70,000 penalty against Booming Games tied to a prohibited auto-play feature. That enforcement backdrop is relevant for Alberta because rapid expansion can test whether a new regulator has the capacity to monitor products, promotions and player safeguards in real time.
Alberta’s officials have framed regulation as a harm-reduction strategy rather than a claim that gambling can be made risk-free. That position reflects the practical trade-off facing provinces: offshore gambling already exists, so governments must decide whether to leave activity outside the formal system or bring it under rules that can be enforced. Alberta’s early account growth suggests many players are willing to use regulated platforms when the product range is broad enough and the brands are familiar.
The stakes now extend beyond Alberta. Other provinces are watching whether Alberta can convert early demand into sustained revenue without inviting backlash over gambling harms. If September’s growth continues, Alberta will strengthen the case that Ontario was not an isolated example but the start of a broader Canadian shift toward competitive provincial igaming markets. If growth exposes compliance gaps or political pressure builds, it could slow that shift. For now, Alberta’s first three months show a market moving quickly from launch phase to material scale, with the same central tension that has defined Canadian igaming since Ontario opened: how to capture existing demand while proving that regulation offers more protection than prohibition or neglect.